How far house prices have risen since the last time rates were this high
The cash rate has reached a 15-year high, and home owners are battening down the hatches to manage the repayments.
First reported 54 minutes ago · latest update 54 minutes ago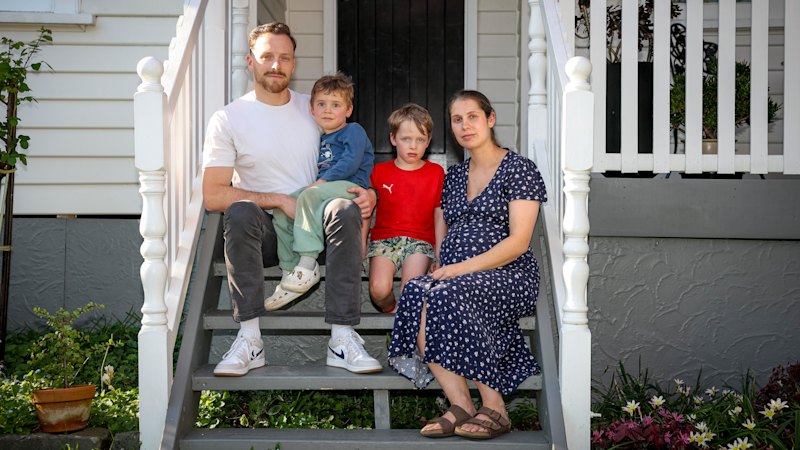
The last time the cash rate was this high, it cost about half as much to buy a house.
Housing wasn’t as expensive relative to incomes, households didn’t have so much debt, and house prices were about to boom as rates dropped.
The Reserve Bank on Tuesday increased the cash rate to 4.6 per cent to quash stubborn inflation.
Last time interest rates were higher was in October 2011, when the central bank held steady at 4.75 per cent, before making a series of cuts from the following month.
In October 2011, Sydney’s median house value was just $598,888 on Cotality data, and $472,705 in Melbourne. It was even cheaper in Brisbane, at $458,356, and Perth, at $460,361.
Cotality research director Tim Lawless said houses have become more unaffordable in the last 15 years, as housing values more than doubled but wages increased about 49 per cent.
“The stark difference compared to 15 years ago is that housing is much more expensive now,” he said.
“Even though interest rates might have been at fairly similar levels 15 years ago, the underlying dynamic of the market is radically different in the sense that housing prices are much higher than incomes and debt levels are also much higher.”
Affordability has worsened on several measures. The national dwelling value to income ratio had risen from 6.5 times to 8.7 times over that period.
Repayments on a new loan then would have taken up about 36 per cent of a household’s pre-tax income, but now would be 51 per cent.
Household debt was at 161 per cent of disposable incomes then, and has risen to 178 per cent now.
“Households have become a lot more sensitive to changes in the cost of debt. And that’s probably amplified significantly given the broader cost-of-living pressures,” he said.
He said it had become harder to achieve home ownership, so some buyers were looking further afield or buying a smaller property.
Even those who accessed the Australian government’s 5% Deposit Scheme needed to show they could repay a 95 per cent mortgage, he said.
Despite this, he noted mortgage arrears are relatively low.
“It won’t last forever,” he said. “Most households seem to be … battening down the hatches and weathering the storm and probably pulling back on things they don’t need to spend on.”
In Melbourne’s Croydon South, Sebastian Kenihan, 37, and his wife Danielle Russell, 34, are preparing for more expensive mortgage repayments – and the birth of their third child.
Kenihan and Russell have two sons, Matthew, 5, and Lachlan, 3½.
The couple upgraded to a four-bedroom home 18 months ago, fixing their interest rate in January for 12 months.
“We were aware of the rumblings of rate increases at the start of the year so we decided to take the opportunity to fix for one year. We should have fixed it for longer, but you don’t have a crystal ball to see what is going to happen,” Kenihan said.
They have not decided on their next move for their mortgage, but have looked at where they can save money.
“We’re minimising the discretionary spending … for meals, we’re cooking ourselves and going to the supermarket, looking at streaming services and checking electricity providers – those larger costs – to keep them on track,” Kenihan said.
The couple has some decisions to make about their finances when their fixed-rate period ends.
“We’re obviously grateful we spoke to our mortgage broker and fixed the mortgage, but it only delays the inevitable of reconsidering what we do,” Kenihan said.
Their mortgage broker, Samuel Power of Loan Market Melbourne, said clients had been planning for higher repayments.
Many were cutting costs, cutting back on takeaway food and food delivery, checking grocery bills, looking for the best deals and sales at local markets, or not taking expensive holidays.
“They’re looking for the mechanisms to limit the damage,” Power said. “It’s been happening for a while now because the cost of living has been so expensive.”
While many were looking to fix at least part of their mortgage, Power warned fixed rates are higher than variable.
“There would still need to be three more rises to be above where fixed rates are at the moment.”
Sydney home owner Samantha Spackman, 35, bought a two-bedroom apartment in Dee Why four months ago – a base after years of moving between rentals.
She previously owned a property in northern NSW for an intended sea-change that never eventuated. She also owns a Queensland investment property.
She was unsurprised by the hike. “I don’t think I’m unprepared for it,” she said. “On top of everything else that continues to rise, it continues to put pressure on, and more stress.”
She is mindful of her spending on items such as groceries and takeaway coffees.
“It’s nerve-racking, the size of the mortgage that I have, being a single home owner not in a relationship, and having to service it myself definitely means that my eyes are on interest rates as they continue to creep up,” said Spackman, who works in marketing for a technology company.
“The size of mortgages that you have to take out to buy somewhere nowadays weighs into that.”
Her mortgage broker, Anthony Landahl, managing director at mortgage broker Equilibria Finance, said some home owners have made extra repayments, while some are refinancing or fixing.
Some are using offset and redraw facilities more strategically, examining discretionary spending or selling an investment property.
Potential borrowers avoid borrowing to their limit, or ask how much they could borrow if there were more hikes.
“The amount of income required to purchase a house from an affordability perspective is now a much larger share than 10 or 15 years ago when interest rates were higher,” he said.
“Now it’s taking two incomes to afford a mortgage, because the size of the mortgages, relatively speaking compared to back then, is a lot larger, so that’s really challenging affordability.”
You have reached your maximum number of saved items.
Remove items from your saved list to add more.
Citations · 2 reports from 2 outlets
Tap a citation to read it above, right here on T.A.M.
How far house prices have risen since the last time rates were this high
The cash rate has reached a 15-year high, and home owners are battening down the hatches to manage the repayments.
54 minutes ago · Melissa Heagney-Bayliss, Elizabeth RedmanHow far house prices have risen since the last time rates were this high
The cash rate has reached a 15-year high, and home owners are battening down the hatches to manage the repayments.
54 minutes ago · Melissa Heagney-Bayliss, Elizabeth Redman