Donald Trump announces temporary fuel‑price cut ahead of US midterm elections
Former President Donald Trump has announced a short‑term reduction in fuel prices in an effort to influence voter sentiment before the upcoming midterm elections. Both Australian outlets describe the move as a desperate, likely short‑lived bluff.
First reported 1 hour ago · latest update 1 hour ago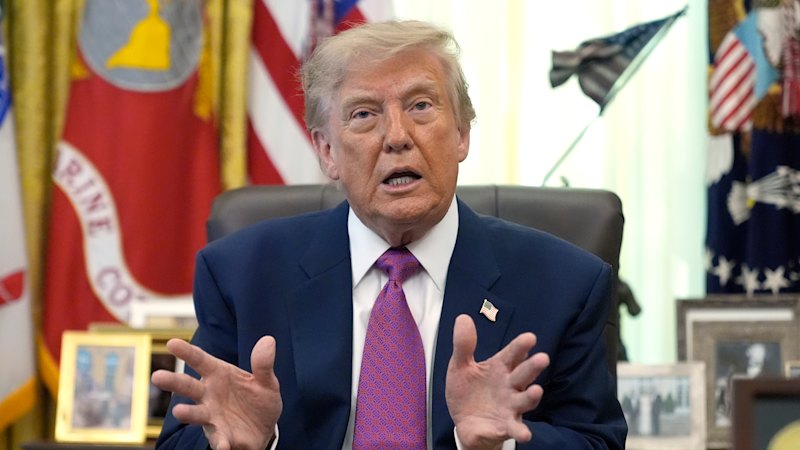
You have reached your maximum number of saved items.
Remove items from your saved list to add more.
Donald Trump coerced G7 countries into a release of their emergence reserves of oil and diesel in an attempt to lower prices in the US ahead of the midterm elections. Will his gambit work?
It might, in the short term, with oil and diesel prices dipping after the announcement that the countries – Canada, France, Germany, Italy, Japan, the United Kingdom, and the United States– would release up to 100 million barrels of oil and diesel over the next four months, including a “front-loaded” substantial release of diesel stocks over the next 20 days.
The announcement was in response to Trump threat to ban US exports of diesel.
With the European Union and UK heavily reliant on imports from the US and the northern winter looming, that was a very direct threat to their economies and societies, even though Trump now says that “we were never going to do it.”
Trump, while toying with the idea of an export ban because record gasoline and diesel prices are hurting US consumers and farmers and adding to Republican fears of a wipeout at next month’s midterms, had been told by the US oil industry that a ban might produce short-term relief but could subsequently exacerbate the problem.
Their advice was that it would lead to a rapid increase in domestic inventories that would inevitably force US refiners and oil producers to cut their production of gasoline, diesel and jet fuel.
Trump’s bluff had some impact. After dipping below $US100 a barrel in response to the G7 announcement, however, the oil price bounced back up to more than $US102 a barrel. US gasoline and diesel prices edged down, but US gasoline prices are still 40 per cent higher than they were at this time last year and diesel is more than 70 per cent higher.
The release is a palliative for the deep wounds in the world’s oil markets caused by Trump’s war in the Middle East.
Releasing 100 million barrels of oil and oil products – and it is the products, particularly diesel, that matter – over four months represents an addition to global supply over less than a million barrels a day.
The G7 statement didn’t detail the split between oil and diesel releases, but the industry view seems to be that it will be roughly 50 million barrels of each.
Global refinery output is currently about 7 million barrels a day lower than at the same time last year. Global oil inventories are at their lowest levels for five years.
Unless and until the Strait of Hormuz is fully re-opened on pre-war terms, war-damaged refineries in the Middle East are back to full production and Russia, whose refineries have been very successfully targeted by Ukraine, resumes exports of refined product, the market for refined products will be short of supply relative to demand.
While the US has claimed to have reopened the strait and says that volumes have been nearing pre-war levels, recent Iranian attacks on tankers transiting the strait – at least four and as many as seven have been targeted in the past week – have again reduced the flow of oil and its derivatives from the region.
It’s also not just about flows. Before the war tanker rates to ship oil via the strait ranged from about $US30,000 a day to more than $US100,000, depending on the size of the tanker. They’re now over $US800,000 a day.
Insuring a tanker used to cost about $US250,000 pre-war. Now, where it is available – a lot of insurers have stopped providing coverage – it can cost up to $US10 million for the larger ships.
For those tankers avoiding the strait and taking longer routes to reach their end markets, there are additional operational costs.
All those new risks and costs are built into oil prices and will remain there unless and until there is a conclusive end to hostilities in the region and something akin to the pre-war norms for transiting the strait are in place.
It would also take months, even years, for the damage to Middle Eastern refineries to be remedied.
Before the war, the Saudis were the world’s second-largest producer of diesel and produced more than 3 million barrels a day of refined products, although about half of that output was devoted to its domestic market. Today its refined product volumes are less than 60 per cent of their pre-war levels.
Releasing G7 stocks may provide temporary relief, but it doesn’t address that underlying shortfall of supply and, on the meantime, runs down the buffers available to deal with the potential for the future shocks that caused to reserves to be built.
Despite the release, the market for diesel could tighten further.
Russia – once the world’s second-largest exporter behind the US, has banned diesel exports until at least the end of this month (more likely indefinitely) because of the damage Ukraine has inflicted on its refining infrastructure. Ukraine has vowed to intensify those attacks.
China – the world’s second-largest consumer of oil and refined products behind the US – has also, again, stopped refined product exports. It was exporting about a million barrels a day before the war.
More fundamentally, those refineries unaffected by the war – predominantly in the US – are operating at near capacity levels, or around 95 per cent of capacity.
The refineries are experiencing massive margins and generating enormous profits, but don’t have the ability to expand production meaningfully and their inventories of refined product have been run down.
US refineries’ diesel inventories are at their lowest seasonal level since data on diesel stocks started being collected in 1982.
With global demand for refined products having recovered somewhat from its nadirs after the outbreak of the war, supply isn’t capable of responding significantly.
The reserves release might temporarily close the gap, but it doesn’t resolve the underlying mismatch of supply and demand and creates the risk that, with depleted inventories, there’s less of a buffer to deal with a prolongation of the conflicts in the Middle East and Ukraine or some new threat to energy supplies.
That suggests oil, gasoline and diesel prices will remain higher for longer. It is, of course, the refined product prices that matter – no-one pours crude into their tanks.
A survey of US oil and gas executives by the Federal Reserve Bank of Dallas last month found that nearly half of them – 48 per cent – expected it would take more than a year for diesel prices to return to last year’s levels.
Trump’s anxiety about the impact of the near-record prices for gasoline and diesel in the US is well-founded.
The higher costs of gasoline and, in particular, diesel – because its fuels trucks, freight trains, ships, tractors, construction machinery and has a host of other industrial applications are starting to feed into goods prices – are feeding into the costs of end-products to customers and the inflation rate. Because of the war, US farmers are experiencing both elevated diesel and (because the Middle East has been a major fertiliser producers) fertiliser prices.
The backlash against the increase in the cost of living and doing business is spreading throughout America, hence Trump’s dismal personal ratings and the prospect of big gains for the Democrats next month.
If sustained at current levels, those higher input costs will both lift the inflation rate and reduce economic activity, risking stagflation.
Even if Trump’s success in “convincing” the rest of the G7 that releasing oil and diesel reserves was in their best interests, the impact so late in the political cycle is likely to be immaterial to the outcome of the elections and the impact of the war in the Middle East on domestic gasoline and diesel prices will still be there and still discolouring the second half of his term as president.
The Market Recap newsletter is a wrap of the day’s trading. Get it each weekday afternoon.
Citations · 2 reports from 2 outlets
Tap a citation to read it above, right here on T.A.M.
Trump’s bluff is too late to save him
Donald Trump just made a desperate move to lower fuel prices ahead of the US midterm elections. The relief, however, is likely to be short-lived.
1 hour ago · Stephen BartholomeuszTrump’s bluff is too late to save him
Donald Trump just made a desperate move to lower fuel prices ahead of the US midterm elections. The relief, however, is likely to be short-lived.
1 hour ago · Stephen Bartholomeusz